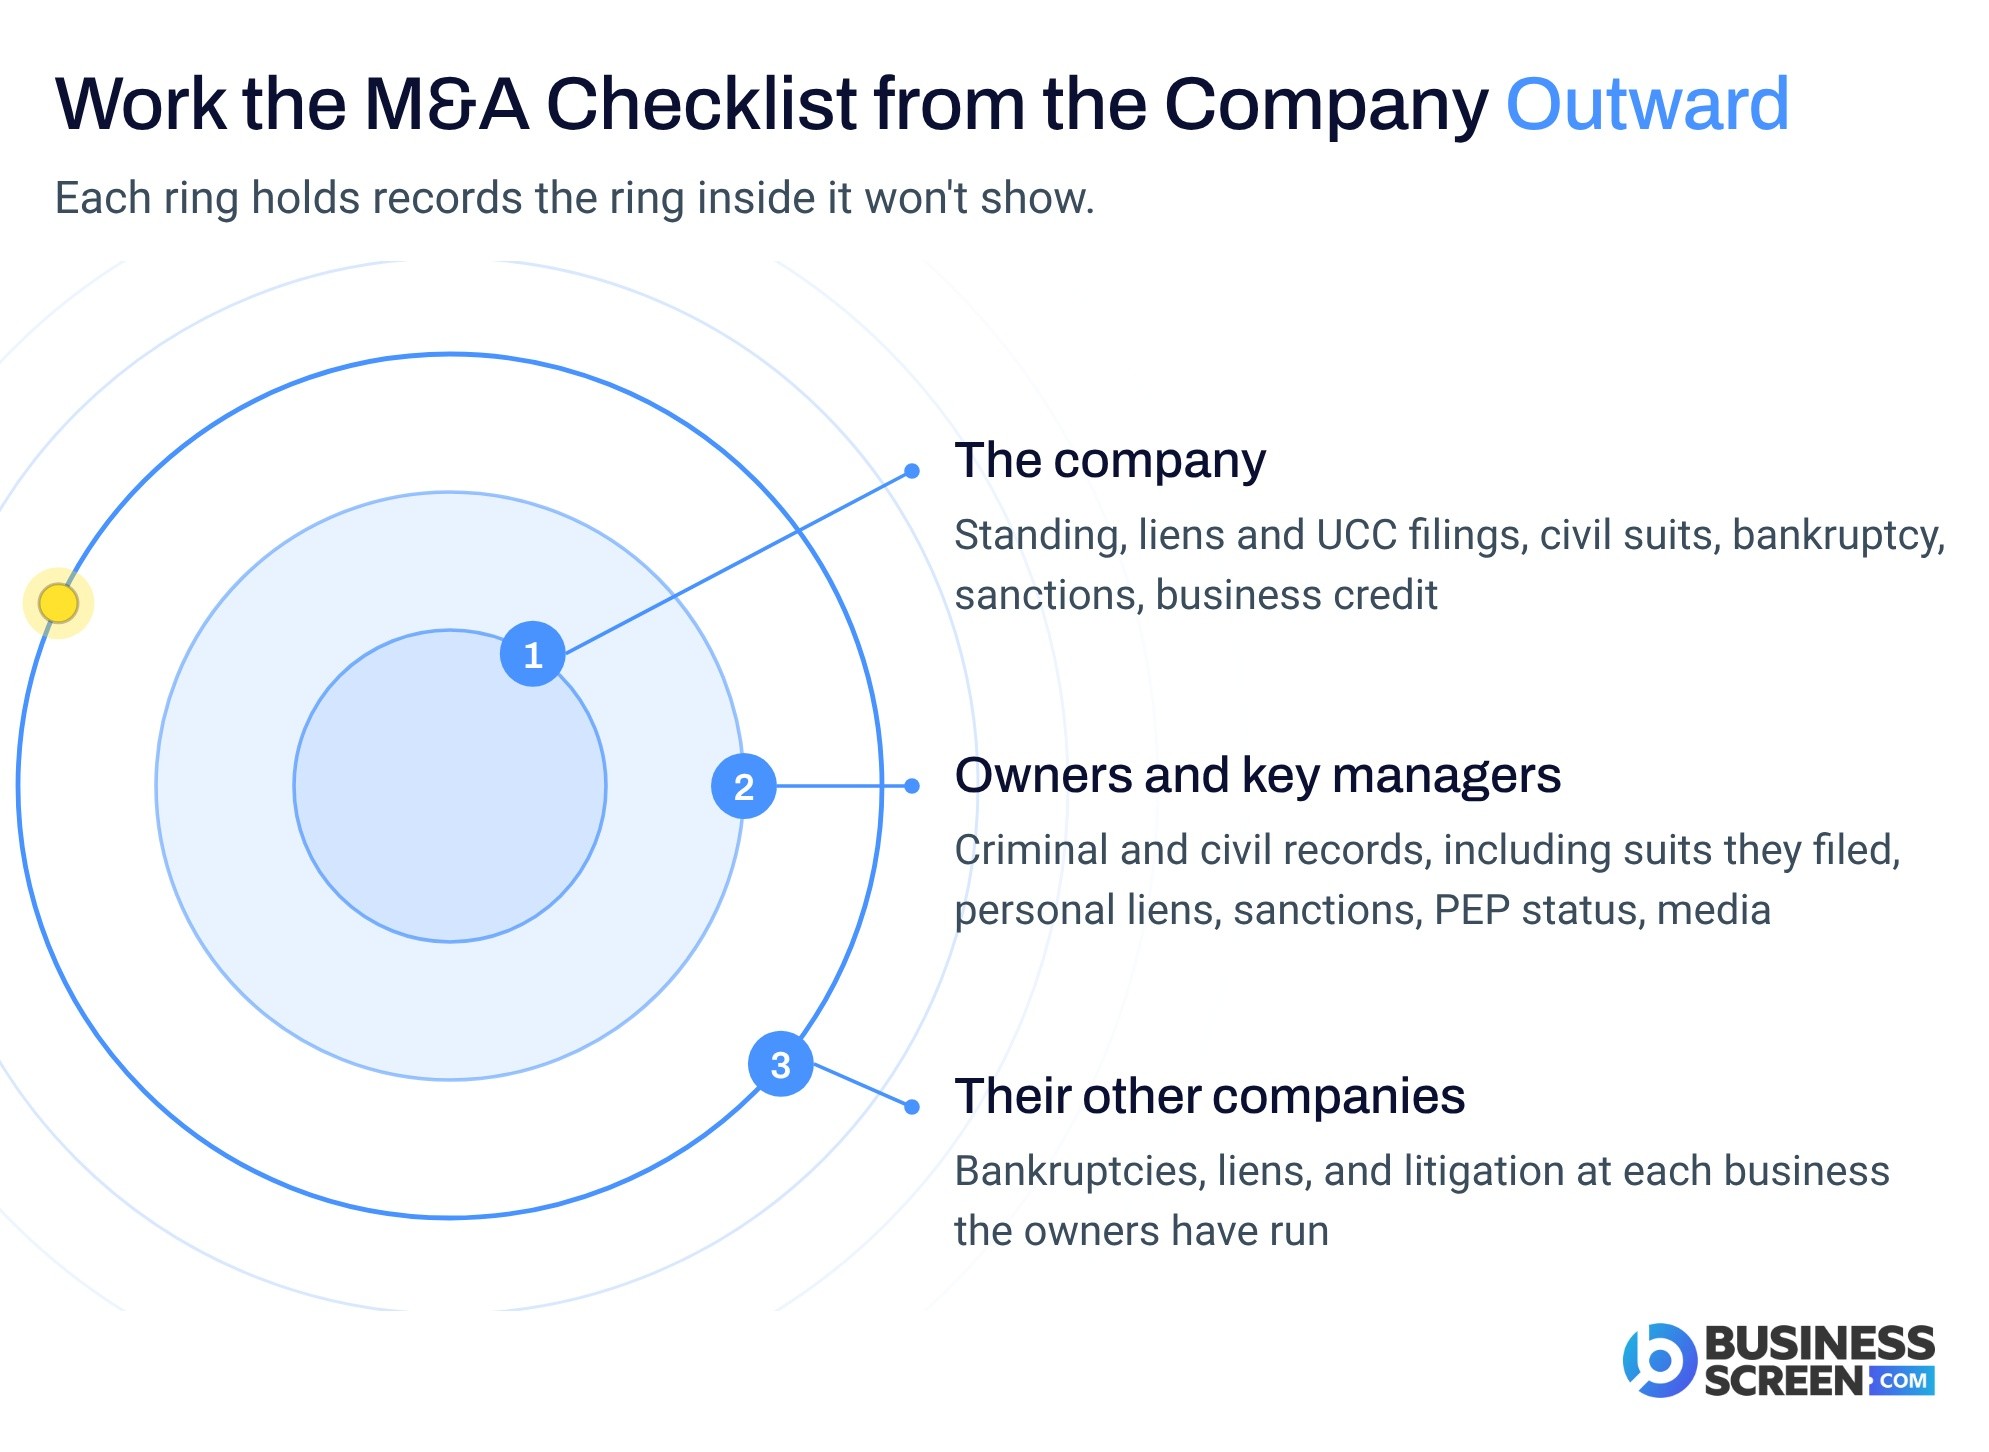
A mergers and acquisitions (M&A) due diligence checklist for the people and entity side of a deal checks whether the target company is the entity the seller describes, whether its owners and key managers carry litigation, liens, criminal history, or sanctions exposure that hasn't come up, and whether the other companies those owners have run hold problems that could follow them into your deal. Those answers come from public records rather than the data room, and they're worth having before you sign.
Financial, tax, and technology reviews run alongside this work, usually led by your accountants and deal counsel. What follows covers the public-record side, in the order most deal teams work through it.
Public records are the part of pre-acquisition due diligence that tests what nobody in the data room is likely to volunteer. The data room holds what the seller chooses to share, while courts, registries, lienholders, and regulators keep records that don't depend on anyone's memory or candor.
The difference shows up in the details. A founder might mention "a dispute with a former partner," and the docket tells you the amount claimed, whether it settled, and who else was named. That makes public records an efficient input to a pre-acquisition risk assessment, and one of the few that doesn't rely on the seller's cooperation. They sit alongside the financial and legal workstreams in the broader M&A due diligence process rather than replacing any of them.
Start with the company itself, because liens, judgments, and secured filings are often recorded against the business rather than any individual. Deal teams coming from co-investing or employment screening sometimes check only the owners, which leaves the company's own record unread. Six areas cover most of what matters.
For owners and key managers, the checklist covers criminal history, civil cases, personal liens and judgments, sanctions and politically exposed person (PEP) status, and adverse media. In a founder-led business these people often stay on to run the company, so their records carry as much weight as its own, a point covered further in why a business background check should cover principals too.
How far back to look is where deal diligence differs most from a hiring check. Employment background checks fall under the Fair Credit Reporting Act (FCRA), which can limit how far back some records are reported, often to 7 years. Diligence that supports a decision about a deal sits outside the FCRA, so it can reach back 20 years across prior addresses and name variations, including dismissed cases. U.S. searches also don't need the owner's sign-off, which the piece on whether a non-FCRA check requires consent explains.
The owners' other companies belong on the checklist because a judgment or bankruptcy recorded against a related business won't appear on a search of the target or the person alone. An owner whose last company closed with unpaid judgments, or a sister company at the same address carrying open liens, can matter as much as anything on the target's own record.
Finding those companies starts with a search for the entities where each owner is listed as an owner, officer, or executive, followed by bankruptcy, lien, and litigation searches on each one. This step does the most work when the company is young and the founder's history is most of the story, as in checking a founder before the investment committee.
When a seller discloses a lawsuit, lien, or past issue up front, the checklist shifts from discovery to confirmation, checking that the disclosure is complete and that the record matches the story. Sellers who volunteer an issue usually aren't hiding it, but the record can still differ on the amount, the status, or whether there's a second case like it.
Pull the court documents and case summaries rather than relying on a database line, so you can set the seller's account next to the filing itself. That documentation also answers the question a lender or co-investor is likely to ask, which is whether you've run your own diligence. If something new turns up, the guide to due diligence red flags covers how to weigh it.
On timing, a common sequence is a lighter check on the company and lead owner before the letter of intent (LOI), then the full owner and management review once exclusivity is signed. Source-level searches generally take a few business days, so ordering a few weeks before close leaves room to follow up on whatever surfaces.
Sell-side due diligence runs the same M&A due diligence checklist on your own company and its owners before going to market, so you see what a buyer's diligence will see while there's still time to resolve it. Owners are sometimes unaware of filings against their own business, such as a judgment from an old vendor dispute or a lien a lender never released.
A satisfied judgment that still shows as open, or a UCC filing from a loan paid off years ago, is easy to clear with the right paperwork and awkward to explain under exclusivity. Running the review early means confirmatory diligence moves faster, management spends less of the sale answering questions, and a late finding is less likely to reopen the price.
How deep each item on an M&A due diligence checklist goes should follow two things, the size of the deal and how much history the owners bring. A decades-old company with the same owners throughout often needs only a database screen at the entity level, while an owner who will run the business after closing, or a founder with several prior companies across states, warrants the full lookback with records pulled from the source.
Treat the first pass as a filter rather than a verdict. When it surfaces something, or when a record doesn't match what the seller disclosed, that's the point to go deeper on that subject rather than on everyone. The tradeoffs between database screening and investigative diligence come down to what a missed finding would cost on this particular deal, and when to escalate a screen covers how to make that call.
If you have a deal under LOI and want a second opinion on which of these checks it calls for, fill out the form through the Get Started button below and our investigators will take a look.