A property manager needs a roofer for a twelve-unit building, so she opens the vendor network her company uses and picks a contractor whose profile says credentialed. Behind that word sits a license number, a certificate of insurance, a W-9, and a set of expiration dates the network tracks so she doesn't have to. That is vendor credentialing doing its job, and it does a lot of it well. The question worth asking is what the word actually certifies on the day she relies on it, and which records nobody was ever asked to look at.
What is vendor credentialing, in practice? A network collects a vendor's compliance documents, verifies them, approves the vendor, and keeps those documents current as they expire. Property management, facilities, and service-provider networks run on this model, and the vendor credentialing services behind them exist because an operator hiring dozens of vendors a month can't verify each one from scratch.
Credentialing vendors once and letting many operators rely on the result is what separates a credential from a one-off check. When a general contractor runs subcontractor prequalification, the contractor is the only party relying on what comes back. On a network, each operator inherits whatever the credential covers and whatever it leaves out, and most of them will rarely look underneath it. Not having to check a vendor's license and insurance themselves is the reason an operator uses the network in the first place, and it is also why the scope of the credential matters more than it first appears.
Most vendor credentialing requirements are written as documents with dates attached, such as a license that expires, a policy term that ends, or a tax form that gets refreshed. The renewal calendar is the engine of the program, and it catches real problems. A policy that lapses at renewal or a license that runs out gets flagged on schedule.
Expiration turns out to be the smaller share of what goes wrong with a credential, though. Across the vendor networks we screen for, 54% of insurance checks turned up at least one coverage line that fell short of what the network required. In 9 of 10 of those cases, nothing had expired. The policy was in force, but the network wasn't named as an additional insured, a required line of coverage was missing, or the insurer was rated below the network's threshold.
License checks follow a similar pattern. When one flags on the networks we screen for, fewer than 1 in 30 of those flags involves an expired, lapsed, or suspended license. More often no matching license can be found for the vendor that submitted it, or the license is active and carries citations or fines. That is why license and certificate verification goes to the issuing board for status and disciplinary history, and why our insurance verification pulls coverage from the vendor's broker and checks it against the network's own requirements rather than reading dates off a certificate. A current document and a compliant vendor are related claims, and a credential is stronger when it is clear about which one it is making.
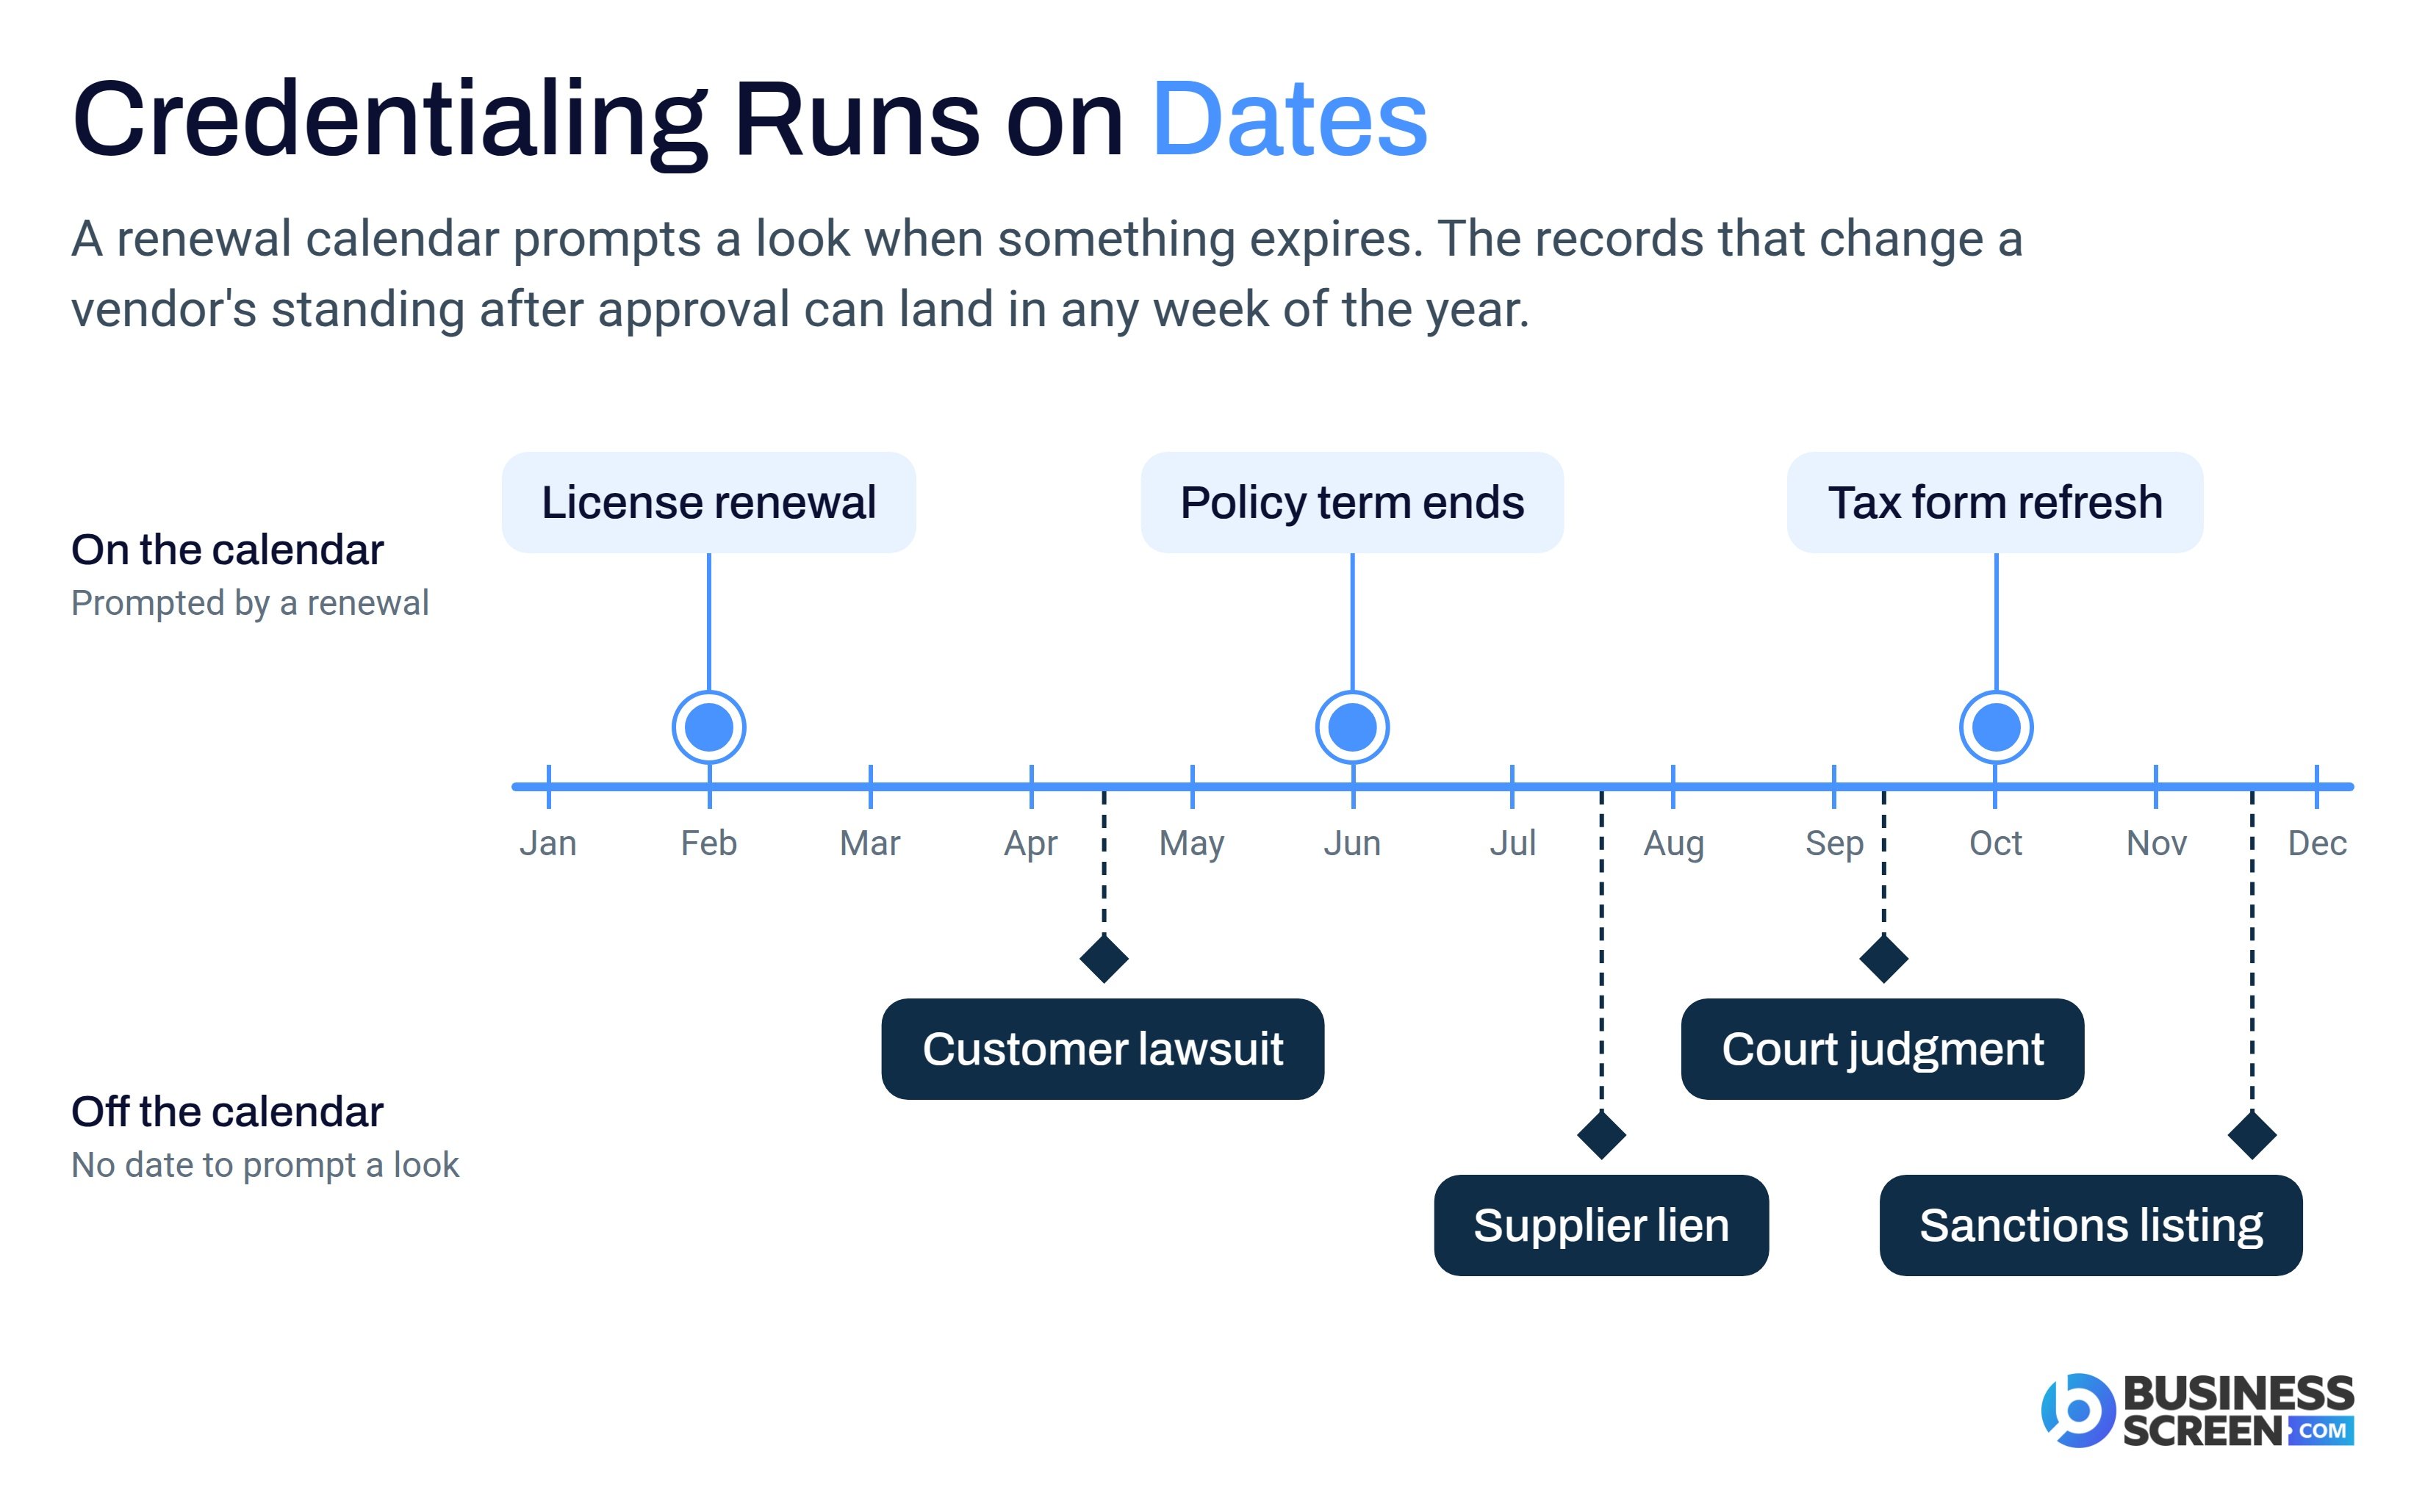
A renewal calendar can only prompt a look at things that carry a date. A lawsuit from a customer, a lien from an unpaid supplier, a court judgment, or a new record on one of the owners can land in any week of the year, and none of them appears on a certificate of insurance or a license renewal. A credentialing program has no scheduled moment to go looking for them.
Operators running vendor programs tend to describe the gap the same way. License and insurance get verified as part of the process, while liens and lawsuits have to be looked up one vendor at a time, which in practice means they often aren't. Those records are public, and liens and judgments say a good deal about how a business handles what it owes, but they sit in court records and county recorders' offices rather than in a credentialing file.
How much does a vendor actually change after approval? We looked at companies our vendor and marketplace clients screened twice. When the second screen came about 6 months after the first, roughly 1 in 12 companies had a new flag. When that flag was a court, lien, or bankruptcy record, it usually wasn't a new event. In 8 of 10 of those cases, the record had been filed before the first screen and simply hadn't shown up yet.
The longer the wait, the more that changes. On one multifamily developer's subcontractor network, companies went about 19 months between screens, and the searches ran county by county. There, 41% came back with something new, and about 2 in 3 of the new court and lien records had been filed after the first screen. Either way, nothing on a renewal calendar would have prompted that second look.
The answer isn't to make credentialing do a job it wasn't built for. It is to be specific about what the credential certifies, and to add a separate layer for the records it was never going to catch.
Start by writing down what credentialed means on your network, including which documents were verified, against which requirements, as of what date, and what falls outside the credential's scope. Operators then know exactly what they are relying on, and a badge doesn't get read as a background check.
Then add a risk screen at approval. A Preliminary Report checks the business for liens, judgments, and bankruptcies, runs sanctions and watchlist screening, and searches adverse media, and it comes back in minutes when it is clean. When something flags, an investigator confirms the hit belongs to your vendor before the report reaches you. The order we would run those checks in, and how to decide on what comes back, is laid out in our seller onboarding checklist for marketplace platforms.
Finally, decide which vendors get re-checked between renewals. Monitoring re-checks previously screened vendors at an interval you set, from monthly to annually, and sends an alert by email, dashboard, or webhook when a new record appears. The tradeoffs against a one-time screen are covered in point-in-time screening versus continuous monitoring. Vendor and provider networks that want this inside their own onboarding flow can connect through our API, which takes roughly five to six hours to integrate with our support.
Most companies come back from a second screen looking the way they did the first time, and that cuts in both directions. For many vendors, documents on a renewal calendar are enough. A vendor who cleans carpets in vacant units twice a year is easy to replace, and monitoring them monthly is cost without much return.
The risk layer earns its place where an operator depends on the vendor, or where the vendor works inside residents' homes, holds deposits, or carries a large share of the work. Think of a roofing contractor on an occupied building, a care provider working in a client's home, or a vendor you would struggle to replace halfway through a project. The same logic sits behind knowing when to escalate a screen. When a re-check flags something material and unclear, an Advanced report sends our investigators to the source records and comes back in two business days, and that is the moment to spend on depth. For the rest, a vendor background check at approval and a clean renewal calendar are often the right answer.
When the program is working, an operator who reads the word credentialed knows which documents were checked, against which requirements, as of what date, whether the vendor was screened at approval, and whether it is being re-checked. Nothing in that description promises more than the program delivers, which is what makes it worth relying on.
If you run a vendor network and want to work out which vendors need more than documents, hit Get Started below and fill out the form. Our investigators can look at your vendor mix and tell you where a lighter check is the right answer and where a risk screen earns its cost.